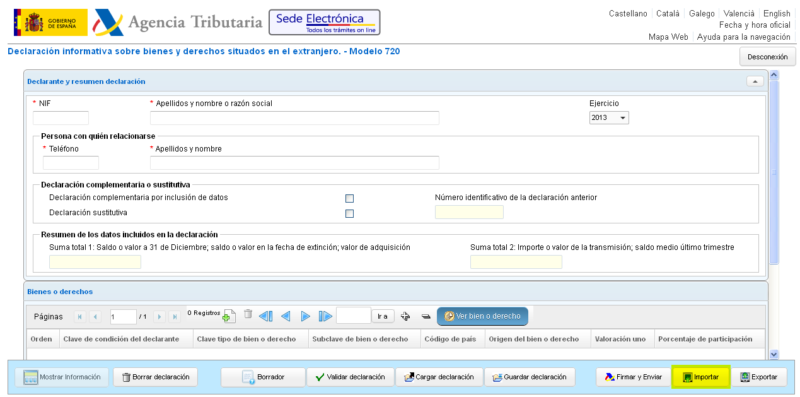
If you’re a Spanish tax resident with assets outside Spain, you probably have to file Modelo 720, the informational return that lists your foreign bank accounts, investments and property. I filed it every year while I lived in Spain, and this guide covers how it works now, after the 2022 changes, plus the practical questions expats tend to get stuck on.
- Who files: Spanish tax residents (and some others who pay IRPF) holding assets abroad.
- What goes on it: three categories, namely foreign bank accounts, foreign securities, insurance and annuities, and foreign real estate. Crypto held with custodians abroad goes on a separate form, Modelo 721.
- Threshold: you file a category when its total value at 31 December is more than 50,000 EUR (for accounts, either the year-end balance or the fourth-quarter average).
- Deadline: 1 January to 31 March, covering your position at 31 December of the previous year.
- Later years: you only file again for a category whose total has risen by more than 20,000 EUR since your last return, or when you stopped holding an asset during the year.
- Penalties: since Ley 5/2022 followed the EU Court of Justice ruling in case C-788/19 (27 January 2022), the general rules for informational returns apply: 20 EUR per missing data item, with a minimum of 300 EUR and a maximum of 20,000 EUR, halved if you file late before Hacienda asks you to. The 150% surcharge and the rule treating undeclared assets as income with no time limit are gone.
Since I received so many requests about this form, I arranged to forward them to tax professionals I trust, so you get professional advice and help (at a reasonable fee) with this complicated declaration.
Click here to get in touch if you want to speak with a tax lawyer or accountant. I’m not qualified to handle individual filings myself, given how different everyone’s financial setup is.
If you want to learn more about Modelo 720 before trusting anyone else with your obligations, read on. My advice is to understand your own tax position, but given the amounts involved, it’s usually worth paying a professional to file.
Spanish tax resident individuals are obliged to report (720 Form) the following assets and rights (including any investments) located outside of Spain to the Tax Authorities:
- Accounts in which the individual is the titleholder, or in which he is representative, authorized person or beneficiary, or in which he has disposal powers.
- Securities, rights, insurance and life or temporary annuities.
- Real estate or rights on real estate.
There will be no reporting obligation for those assets or rights which value (considered in aggregate for each group of assets listed above) is lower than Euros 50,000. The deadline for filing the 720 Form is from 1 January to 31 March of the year following that for which the information must be reported.
In subsequent years you only need to file again for a category whose total value has risen by more than 20,000 EUR since your last return. You must also file whenever you stopped holding an asset during the year, for example when you close an account or sell an investment.
What Changed in 2022
The European Commission challenged Spain’s Modelo 720 penalty regime, and on 27 January 2022 the EU Court of Justice ruled in case C-788/19 that the penalties were disproportionate and restricted the free movement of capital. Spain responded with Ley 5/2022 (in force since 11 March 2022), which:
- Removed the special Modelo 720 penalties, including fixed fines of 5,000 EUR per data item and the 150% surcharge, so the general penalties for informational returns in articles 198 and 199 of the General Tax Law now apply.
- Changed article 39 of the IRPF law so you can rebut a charge on undeclared foreign assets by showing you held them before the limitation period, instead of having them taxed as unjustified income with no time limit.
The court didn’t strike down the reporting obligation itself, so the form still has to be filed. Before 2022 the stakes were high enough that people facing large fines took Spain to court; today a late or incomplete return is an ordinary administrative penalty, not a financial disaster.
Filling it in is still fiddly, especially the first time. Many accountants and gestores don’t handle it, and those who do charged anywhere from around 150 EUR to over 1,000 EUR when I asked for quotes. You still provide all the documents and figures yourself; the adviser guides you on what’s needed and files the form for you.
If you want to dig deeper, the Agencia Tributaria has an extensive Modelo 720 FAQ (in Spanish). Below are the questions expats ask most often. They aren’t official answers, just the cases I’ve come across and how they’re treated, with the official source where there is one.
Question: When is the Modelo 720 deadline?
Between 1 January and 31 March each year, covering the assets you held abroad at 31 December of the previous year. Crypto on Modelo 721 has the same window.
Question: What are the penalties for Modelo 720 now?
Since Ley 5/2022, missing or late returns fall under the general penalty for informational returns: 20 EUR per data item, with a minimum of 300 EUR and a maximum of 20,000 EUR. If you file late before Hacienda contacts you, the penalty is halved to 10 EUR per item, with a minimum of 150 EUR and a maximum of 10,000 EUR.
Question: Do you need to report money invested in crowdlending platforms like Mintos, Twino, Bondora etc?
Hacienda says you don’t need to declare the loans themselves. You only need to declare them if they’re represented by securities. For example, some property crowdfunding platforms issue you shares or notes for your investment, and in that case you have to declare those.
However, if the cash balance in your account on the platform is stored in an omnibus account like Lemon Way and it is directly linked to you, you then need to declare that cash balance as at end of year. The platform should be able to give you this information.
Source (Agencia Tributaria FAQ)
Question: Should your spouse fill in the modelo 720 if the assets are in your name?
If you are married under the community of property regime (gananciales), both spouses must file separate Modelo 720 declarations covering the same assets. The declared value is always the full amount, never prorated. Both spouses declare the same total value for each asset, and the ownership percentage is noted separately on the form.
Assets in one spouse’s name: The spouse who is the actual owner (titular) declares the asset with condition code 1 and 100% participation. The other spouse declares the same asset with condition code 8, noting “gananciales” as the type of ownership, and 50% participation.
Joint accounts (for example, a brokerage account held in both names): Both spouses declare with condition code 1 and 50% participation each, since both are titulares.
Shares in a foreign company owned by one spouse: The owning spouse declares as titular (condition 1, 100%). The other spouse declares the same shares under gananciales (condition 8, 50%). If that company in turn owns another company, the second company is also declared by both spouses: the owning spouse notes “indirect title” and the other spouse notes “gananciales indirect.”
Securities held through a brokerage: Each individual security (stock, ETF, fund) is declared as a separate record with its own ISIN. They are not declared as a single brokerage account. If the brokerage account is joint, both spouses declare each holding at 50%.
Because both declarations contain the same assets at the same full values, the total valoracion on both declarations will be identical. Only the condition codes and participation percentages differ between husband and wife.
Question: Should bank accounts with a balance of zero be declared?
Yes, you need to declare all accounts outside of Spain once the sum total is 50,000 euro or higher. Empty accounts will still have to be declared.
Question: Should you declare life assurance accounts held with banks?
Yes, provided that it’s an account where you automatically deposit money every month. These are mixed savings and life assurance accounts, so you declare them. If you’re just paying a monthly or yearly premium to an insurance company for a life assurance policy, then you don’t declare it.
Question: If there is a change of 20,000 euro or more in any category, do you declare all the items in that category or just the particular item that changed its value?
When the total value of a category has risen by more than 20,000 euro compared to the last declaration, you must re-declare all items in that category with their current values, not just the item that triggered the change. For example, if you open a new brokerage account worth 30,000 euro and your last full investment declaration was three years ago, every investment in that category needs to be re-declared with updated amounts.
Assets you stopped holding during the year (sold investments, closed accounts) must always be declared, whatever the 20,000 euro test says.
Question: Should cryptocurrencies be declared on the Modelo 720?
Not on the Modelo 720. Since the 2023 tax year, crypto held with custodians outside Spain goes on a separate form, Modelo 721 (Orden HFP/886/2023), with the same 50,000 EUR threshold and the same 1 January to 31 March deadline. Crypto you hold in your own wallet, where you control the private keys, is outside its scope.
Question: A resident in Spain is a partner of a non-resident society (first level) that in turn is a partner of other non-resident societies (second level) What obligations to inform does the resident have with respect to the non-resident organisations and the goods owned by said organisations?
The resident must declare his or her participation in the first non-resident company. The prior must be applied as long as the non-resident companies carry out an economic activity through the corresponding organisation of material resources and staff, that is, that they do not have an instrumental character whose purpose is merely the indirect control of the goods on behalf of the real owner.
Question: Do I need to declare the bank accounts of a foreign corporation in which I am a 100% shareholder?
Yes, since you would be considered the beneficial owner of the bank accounts, even though they are in the name of your company.
Question: Do you need to declare money in virtual bank accounts such as Wise, N26 or Revolut?
If the virtual account has all the details of a traditional bank account, you should declare it along with the rest of your bank accounts.
Question: Do you need to declare the balance of your PayPal account?
PayPal accounts don’t fit any of the category definitions that apply to the modelo 720 and are thus not included. However, unfortunately, Spanish Hacienda loves to leave grey areas in these matters and have people worry unnecessarily instead of explaining exactly what to include and what not.
In a question that was sent to Hacienda, they hinted that you might need to include PayPal accounts, by replying in the following manner:
Por su parte, el portal de “PayPal” define el servicio que presta del siguiente modo:
“PayPal permite a las empresas o consumidores que dispongan de correo electrónico enviar y recibir pagos en Internet de forma segura, cómoda y rentable. La red de PayPal se basa en la infraestructura financiera existente de cuentas bancarias y tarjetas de crédito para crear una solución global de pago en tiempo real. Le ofrecemos un servicio especialmente pensado para pequeñas empresas, vendedores por Internet, particulares y otros a los que no satisfacen los mecanismos de pago tradicionales.”
Finalmente, respecto de la declaración de la cuenta PayPal, podría entenderse, en su caso, que dicha cuenta debe tomarse en consideración a efectos del Impuesto sobre el Patrimonio, o de la obligación de declarar bienes situados en el extranjero.
In my view, if you have significant amounts of money in your PayPal account and use it as you might use a savings account at a bank, you might want to declare it just to be safe. Having said that, I don’t know how you would actually go about declaring it since PayPal does not give you any account number that you would need to put in on the modelo 720 form. So, in the end, you’re just left with doubts.
Question: How is the value of a foreign company determined, given that it is not quoted on any stock exchange and is hence a private company.
The valuation will be calculated with the rules established in the Spanish Law 19/1991 regarding Wealth Tax. Insofar as it is not a company with representative securities traded on organized markets or other specific features, it is necessary to refer to article 16 on other securities that represent the participation in equity of any type of entity.
“En el caso de que el balance no haya sido auditado o el informe de auditoría no resultase favorable, la valoración se realizará por el mayor valor de los tres siguientes: el valor nominal, el valor teórico resultante del último balance aprobado o el que resulte de capitalizar al tipo del 20 por 100 el promedio de los beneficios de los tres ejercicios sociales cerrados con anterioridad a la fecha del devengo del Impuesto”.
This article indicates that the valuation of this type of shares will be carried out at the theoretical value resulting from the last approved balance, provided that it has been submitted to review by auditors. If this is the case of the company, the valuation must be made in accordance with the last approved and audited balance sheet available. As an aside, note that for wealth tax purposes, you can use either the value of the company as at 31st December of the previous year, or the value of the company as determined by the latest published accounts, even if they were published after the 31/12, as it is deemed that the later accounts would be even more accurate as a valuation method. See this page (in Spanish) where this update is explained.
The theoretical value is obtained by dividing the net equity figure by the number of shares, by performing the following operation:
Theoretical value = Net equity / Number of shares in which the share capital is divided.
However, in case the last approved balance has not been audited, the valuation should be made for the greater value of the following three:
- The nominal value.
- The theoretical value resulting from the last approved balance.
- The result of capitalizing at a rate of 20% the average of the net profits of the three fiscal years closed prior to the date of accrual of the tax.
This is a simplified way of valuing a company, when compared to more complex methods used by investors, but it’s the one we need to use to calculate the value for the modelo 720 form.
Filling in the form yourself VS Hiring someone to do it
Be aware that lawyers and accountants can charge very random fees for helping out with this report. I’ve been given quotations ranging from €150 to €1500 and upwards, and that was sight unseen, not taking into consideration the complexity or lack of for each individual’s declaration. It was hard to find someone that I could trust and that wouldn’t fleece me with charges for what essentially is a simple model to fill in, especially for someone knowledgeable like an accountant or lawyer. If you’re looking for someone to help out with your declaration, get in touch and I’ll put you in touch with a tax professional I trust.
You could fill it in yourself too, but even though I knew how to, I preferred hiring a well-known firm to do it for me. When you make a submission the form includes the name of the person or company submitting the form. My opinion is that Hacienda is more likely to go after foreign-sounding names who submit the form without any outside help, rather than if they see a form being submitted by a Spanish company.
The EU Court of Justice only struck down the penalties, and the reporting obligation itself stands, so the best you can do is fill it in properly and avoid complications with Hacienda. Keep in mind that even if you get accused unjustly of filling it out wrongly, you will still need to spend a lot of time and hassle to go through the Spanish courts and depend on them to issue the final ruling. It’s better to do it right the first time around.
Note that this is just a summary of my research on the topic and my discussions with various tax consultants. It should not be taken as tax advice. When in doubt, you should always consult a trusted tax consultant to help you fill out this submission. The information could also be out-of-date as new laws and changes to existing legislation happens regularly.
Further reference
- Agencia Tributaria: Modelo 720 filing page (in Spanish)
- Agencia Tributaria: Modelo 720 FAQ (in Spanish)
- Ley 5/2022, which changed the penalty regime (BOE)
- Orden HFP/886/2023, which created Modelo 721 for crypto (BOE)
- REAF – More questions and answers (in Spanish)
Related





Hi
As a married couple surely both should declare 50 % each
Also if accounts were opened before marriage Do they still need to be be declared by both
Hello Jean,
Many thanks for your very useful web page. I filed a 720 for 2021 with all the shares I owned, and last year I bought more of one of the shares on 3 occasions, then sold some of the same shares. As an example, I had 100 shares in 2021, then in 2022 bought 10 more 3 times, then sold 5. Do I report the 4 new 2022 transactions separately in the 720, do I report 1 new entry for 25 shares (10 + 10 + 10 – 5), or do I report a modification to the previous 100 entry for 125?
Do I also have to report again all the shares I already had in 2021 even though the total value hasn’t increased by 20,000?
Many thanks,
Balor
HI,
Your information was really useful now that the US company that I work for has granted me some shares. I would like to get in touch with any of the gestures that you suggest that work in BCN.
I will appreciate it if you can share these with me,
Cheers!
Yes shoot me an email and I’ll put you in touch.
I keep coming back to this article every time the dreadful March 31 deadline rolls around. I thought you might want to update this post now that the European court has officially ruled against Modelo 720 penalty regime. Not that this won’t continue be a headache, but at least the penalty is supposedly less scary. 🤷♀️