I’ve invested in European P2P lending for years and lived through the good times and the platform collapses. This guide is everything I wish I’d known when I started: how it actually works, what returns are realistic, where the real risks hide, and how to build a portfolio that survives when one platform inevitably disappoints you.
If you’re after specific platform recommendations rather than the full picture, jump to my 2026 P2P platform rankings. Otherwise, read on.
What Is P2P Lending?
Peer-to-peer lending connects people who want to lend money with people who want to borrow it, cutting out the bank in the middle. You, the investor, fund small slices of loans. Borrowers repay the principal plus interest over time, and that interest is your return.
In Europe, most platforms don’t originate the loans themselves. They act as a marketplace: loan originators (consumer lenders, car-finance firms, agricultural lenders) issue the loans, then list them on a platform like Mintos or Nectaro for investors to fund. You’re effectively buying exposure to a pool of loans, often with a buyback guarantee from the originator if a borrower defaults.
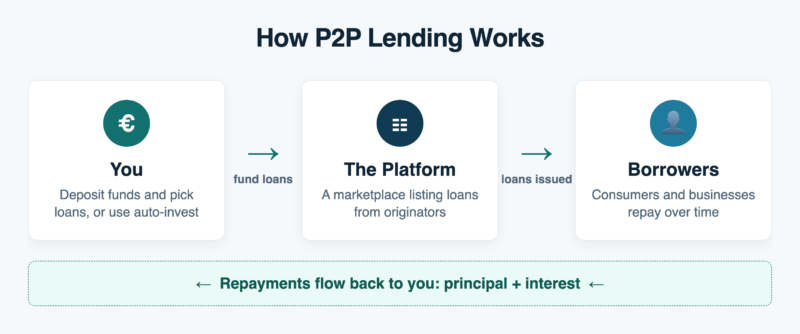
The mechanics are simple from your side: you deposit money, choose loans manually or let an auto-invest tool spread it for you, and interest accrues as borrowers repay. Most platforms let you start with as little as €10 to €50.
How P2P Platforms Make Money
Platforms earn from the spread and from fees charged to loan originators or borrowers, not usually from you. Many European platforms are free for investors, with no deposit, account, or investment fees. A few charge a small fee to sell loans early on a secondary market. Always read the fee page, but the headline rate you see is generally what you earn.
What Returns Can You Expect?
European consumer P2P lending has settled into a fairly consistent band. In 2026, advertised net returns on the major platforms run roughly:
- 9% to 11% on large, diversified consumer-loan platforms
- 11% to 13% on higher-yield platforms and shorter-term loans
- Occasionally higher on niche or business/property loans, with correspondingly higher risk
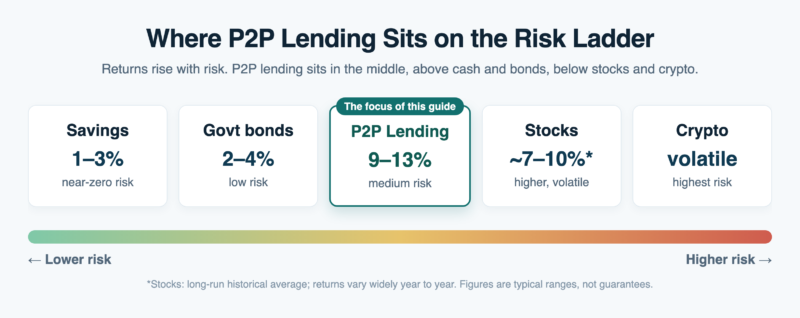
These are not guaranteed. The advertised rate assumes borrowers repay and, where offered, that buyback guarantees are honoured. Treat the headline number as a best case and expect your realised return to be a little lower once you account for cash drag (idle money waiting to be invested) and the occasional loss.
Is P2P Lending Safe? The Real Risks
P2P lending is not a savings account. Your capital is at risk, there’s no deposit insurance, and the failures I’ve watched over the years were almost never about individual borrowers defaulting. They were about the platform or the loan originator. The risks worth understanding:
- Platform risk: the platform itself goes bust or is fraudulent. This is the one that wipes people out. Stick to established, regulated platforms with a real track record.
- Loan originator risk: on marketplace platforms, the company that issued the loan (and stands behind the buyback guarantee) can fail. A buyback guarantee is only as good as the originator backing it.
- Borrower default: the most visible risk but usually the most manageable, because diversification across thousands of small loans smooths it out.
- Liquidity risk: your money is tied up in loans. Secondary markets help, but in a crisis they dry up exactly when you want out.
- Currency risk: loans in a currency other than your own add exchange-rate swings on top of credit risk. Euro-based investors remove it by sticking to euro loans.
- Macro risk: a recession pushes up defaults and squeezes originators and platforms at the same time. European P2P lending hasn’t yet been through a severe, prolonged downturn, so size your allocation with that in mind.
The short version: respect the risk, size your allocation accordingly, and never put in money you can’t afford to lock up or lose.
Once you’re in, check your platforms a few times a year. Slowing repayments, rising defaults, withdrawal delays and vaguer reporting are the early signs that it’s time to stop reinvesting and start withdrawing.
ECSP Regulation: What It Means for You
The European Crowdfunding Service Providers (ECSP) regulation brought much of the sector under a single EU licensing framework. For investors, that’s a meaningful upgrade: licensed platforms face capital requirements, disclosure rules, and supervision, and a licence passports across the EU.
It isn’t a guarantee against loss, and not every platform or loan type falls under it. But “is it ECSP-licensed (or otherwise properly regulated)?” is now one of the first questions to ask before funding a platform. Regulation doesn’t make a platform safe; it raises the floor.
Who Can Invest in P2P Lending?
Most European platforms accept investors who are at least 18, hold an EU/EEA (and often UK or Swiss) bank account, and can pass standard identity checks. You don’t need to be wealthy or accredited. The practical barrier is lower than almost any other asset class: a working SEPA bank account and a passport are usually enough.
Moving Money In and Out
Deposits and withdrawals run over SEPA bank transfers, which most digital banks send for free. A deposit usually lands in one or two business days, or within seconds if the platform accepts instant SEPA. Anti-money-laundering rules mean the money has to come from an account in your own name, so transfers from joint or third-party accounts are normally refused.
Getting money out takes longer than the transfer itself. Cash sitting idle on a platform can usually be withdrawn within one to three business days, but money tied up in loans has to be repaid or sold on the secondary market first, often at a discount. If you need the cash by a set date, start at least a week early. Running all your P2P transfers through one dedicated bank account also makes the year-end tax paperwork much simpler.
How to Choose a Platform
After years in this market, my checklist is short:
- Track record: years in operation, ideally through a downturn. New and shiny is a red flag, not a feature.
- Regulation: an ECSP licence or equivalent oversight.
- Transparency: clear loan data, real financials, named people behind it.
- Returns that make sense: a rate far above the market average is a warning, not a bargain.
Applying that checklist, Nectaro comes out on top in 2026, followed by Mintos (the largest and most diversified, though its recovery backlog and fees are worth understanding first, as I explain in my Mintos review) and PeerBerry (the strongest track record). You’ll find all 11 platforms compared on returns, regulation and risk in my ranked list of European P2P platforms.
How to Diversify Across Platforms
The single most important rule in P2P lending: never trust one platform with all your money. The whole game is surviving the failure of any single platform without it hurting too much. That means spreading across several, not just across many loans on one.
A sensible structure for, say, a €10,000 P2P allocation might look like:
- 40% across one or two large, established platforms (your core)
- 40% across two or three higher-yield platforms with solid track records
- 20% held back as cash or in your most liquid platform, ready to redeploy
The exact split matters less than the principle: if any one platform vanished tomorrow, you’d be annoyed, not ruined. For concrete head-to-head picks, I’ve compared the main options directly, for example Nectaro vs Mintos, and listed the strongest Nectaro alternatives.
P2P Lending and Taxes
Interest from P2P lending is taxable income in most countries, and it’s your responsibility to declare it; the platforms generally don’t withhold tax for you. How it’s taxed depends on where you live. I’ve written separately on how P2P lending income is taxed, and for Spanish residents, foreign-held P2P accounts can also trigger the Modelo 720 reporting obligation. Keep clean records of your interest earned per platform; most platforms provide an annual tax statement.
Alternatives to P2P Lending
P2P lending is one tool, not a whole portfolio. If you like the idea of income-generating alternatives but want to spread beyond consumer loans, the natural neighbours are real estate crowdfunding (property-backed loans, often with collateral) and dividend stocks or bond funds for the more liquid, regulated end. Each has a different risk profile; the point is that P2P should be a slice of your income allocation, not the entire thing.
The premium is smaller than it was when savings accounts paid nothing. Insured euro savings accounts and investment-grade bond funds now pay low-to-mid single digits with easy access to your money, and real estate debt deals pay high single digits with property as collateral. P2P’s extra few points are your pay for giving up liquidity and deposit protection. That trade makes sense for part of your money.
Key P2P Lending Terms
- Buyback obligation: the originator’s promise to buy a loan back from you once it’s late by a set number of days, usually 60. It used to be called a buyback guarantee, but it’s only as good as the originator’s finances.
- Skin in the game: the share of each loan the originator keeps on its own books. The bigger it is, the more the originator’s interests line up with yours.
- Cash drag: money sitting uninvested in your account because no loans match your auto-invest settings. It pulls your real return below the advertised rate.
- Secondary market: where investors sell loans to each other before they mature. It’s your main route to an early exit, and it can dry up in a crisis.
- Bullet vs. annuity loans: a bullet loan pays interest along the way and the principal at the end; an annuity loan repays both in regular installments.
- Loan-to-value (LTV): the loan amount as a share of the collateral’s value. A 50% LTV means the property is worth twice the loan.
- XIRR: the annualized return on cash flows that arrive at irregular dates. It’s the right way to measure what you actually earned across deposits and withdrawals.
Conclusion
P2P lending has matured a lot. Regulation is tighter, the strongest platforms have real track records, and double-digit returns are still achievable for investors who respect the risks. The investors who do well aren’t the ones chasing the highest advertised rate; they’re the ones who diversify across solid platforms, keep some liquidity, and treat it as one part of a broader plan.
If you’re ready to start, the fastest way in is my ranked, regularly updated platform list.
Frequently Asked Questions
What returns can you realistically earn from P2P lending?
In Europe in 2026, net returns typically run from around 9% to 13%, depending on the platform and loan type. These are not guaranteed; your realised return is usually a little lower than the advertised rate once you account for idle cash and occasional losses.
Is P2P lending safe?
It carries real risk and there’s no deposit insurance. The main danger is platform or loan-originator failure rather than individual borrowers defaulting. You manage it by sticking to established, regulated platforms and diversifying across several of them. Never invest money you can’t afford to lock up or lose.
How much money do I need to start P2P lending?
Very little. Most European platforms let you start with €10 to €50. The practical requirements are being 18 or older, having an EU/EEA (often also UK or Swiss) bank account, and passing a standard identity check.
How many P2P platforms should I use?
More than one, always. The biggest risk is a single platform failing, so spreading across three to five solid platforms is more important than holding many loans on just one. My P2P platform rankings cover the options worth combining.
Do I have to pay tax on P2P lending income?
Yes, in most countries interest from P2P lending is taxable and you must declare it yourself. The exact treatment depends on your country of residence. See my guide on how P2P lending is taxed, and note that foreign-held accounts may trigger reporting duties such as Spain’s Modelo 720.
Related




Hi Sir,
I have red somewhere that Mintos is not free for a French man.
In other words I cannot invest in Mintos because I am French.
Can you say the same,
Smiling Paul
PS: excuse my bad English!
thax
Why do you recomend Bulkestate? For the level of transparency?
I also like Viainvest for the track record and transparency.
And what´s your opinion for Crowdestor?
I should have probably made a separate category for real estate crowdfunding websites, in which I would also include Reinvest24 and Property Partner.
I’ll update the post.
Thanks for your post. What makes you recommend those 3/4 platforms over the others?
Several factors, I would say these are some of them that are important for me:
Happy to answer other questions you may have and discuss further.
Thanks for your replay Jean. Do you no longer recommend Twino?
Did you try any factoring P2P sites yet? Investly seems interesting and has a low default rate. I’m not sure I understand how it works yet though.
All thes best
Thanks! Happy first advent.