For many years I struggled to understand the money lingo in American movies and books. Here are the terms you’re most likely to run into, and what Europe has instead.
If you need me to explain anything else just leave a comment and I’ll do my best.
Are There Credit Scores in Europe?
Yes, most European countries track your credit history, but few have a single, all-purpose consumer score like the American FICO score, and a score from one country doesn’t follow you to another.
In the US, a good credit score decides whether you get a mortgage, a car loan or an apartment. The best-known score comes from FICO (Fair, Isaac and Company), founded in 1956 by engineer Bill Fair and mathematician Earl Isaac. FICO scores are the standard measure of consumer credit risk in the US, and the company now operates in more than 80 countries.
In Europe, it depends on the country:
- UK: the closest to the US. Credit reference agencies such as Experian, Equifax and TransUnion each calculate a score from your borrowing and repayment history. Paying a credit card in full every month builds that history, while living only on cash and savings leaves you with a thin file that can make a mortgage harder to get.
- Germany: SCHUFA, a private credit bureau, scores most adults. Landlords often ask for a SCHUFA report before renting out a flat.
- Netherlands: BKR keeps a central register of loans and missed payments that lenders check before granting credit.
- France and Spain: there’s no general consumer score. Banks check negative registers (the Banque de France’s FICP file of repayment incidents, or the Bank of Spain’s CIRBE risk register and private files like ASNEF) and then decide based on your payslips, contracts and assets.
So in most of continental Europe, a bank deciding on a loan looks at your income, your existing debts and whether you appear on a defaulters’ list, rather than a three-digit number.
Credit Card Points and Rewards
In the US, credit cards are everywhere. It’s common to hold several and chase points, cashback and sign-up bonuses. In much of Europe, people pay with debit cards, and many don’t own a credit card at all.
The main reason European rewards are so much smaller is regulation. Since 2015, the EU’s Interchange Fee Regulation has capped the fee banks earn on consumer card payments at 0.3% of the transaction for credit cards and 0.2% for debit cards. US card issuers earn far more per transaction, plus high interest from cardholders who don’t clear their balance, and that money funds generous rewards.
The flip side is that US merchants pass card fees on through higher prices, and people who carry a balance end up paying for everyone else’s points.
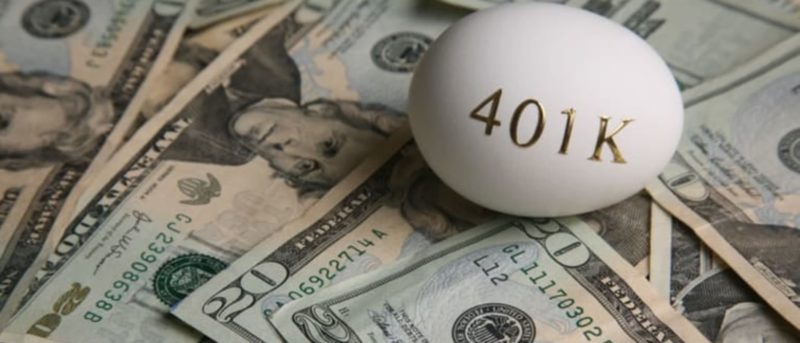
401(k)
A 401(k) is a US workplace retirement plan, named after the section of the tax code that created it. Employees can put part of their salary in before tax, employers often add a matching contribution, and the money grows tax-deferred until retirement.
Europe has workplace pensions too, but each country runs its own system. In the UK, employers must automatically enroll eligible staff in a workplace pension and contribute to it. Germany has the occupational pension known as betriebliche Altersversorgung, and in the Netherlands most employees are covered by sector-wide pension funds. In countries like Spain, workplace schemes are much less common and the state pension does most of the work.
Related




In the US the credit score systems proves to be a scam in itself. This is private information that is opened to anyone. Each and every time a company has access to a person’s credit score you loose points and you receive unwanted junk mail. Another aspect of the US credit score reflects punishing people without debt, meaning, if you have no debt and have always paid on time you loose points instead of gaining. Basically the US credit score system forces people to be in debt in order to maintain a good score.
The United Kingdom has an equivalent to 401k called Workplace pension and in current form, it amounts to 8% of employee’s gross annual income. It is seen as a top-up to government-funded State Pension which isn’t considered sufficient enough to live on. Contributions commonly get split 5% employee and 3% employer, however, an employer can pay more towards it (ie. Sainsbury’s employees have 4 + 4 split) or allow above minimum contributions. All depends on the scheme they chose.
There is also points system in place which is based on many factors. Some of them are income, debt levels, keeping up with repayments, address history, property ownership, electoral registration and more. Financial companies use own data or reach out to credit score agencies which keep track of our points changes. If you are after credit product you need to meet the requirement and be able to afford it or risk being rejected. From experience – it works ok most of the time.