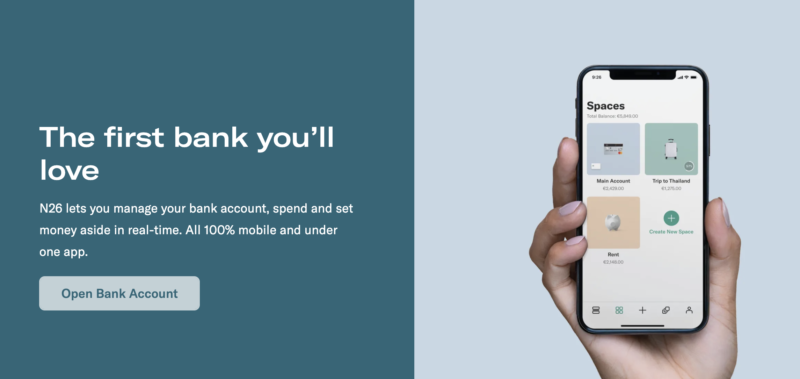
I’ve used N26 for several years alongside Revolut, as a complement rather than a replacement. If you’re considering N26, that context matters: I’m not going to tell you it’s the only account you’ll ever need. But I am going to tell you why it earns a place in your wallet.
The short version: yes, N26 is a good bank for everyday euro banking. It’s a well-regulated, clean, focused European bank with a German banking license, deposit protection up to €100,000, and something Revolut still doesn’t offer: a full desktop interface you can use from any browser. It’s a weaker fit if you want the widest range of investing and travel extras in one app. Plans and features below were checked in October 2026.
What Is N26?
N26 was founded in 2013 in Berlin by Valentin Stalf and Maximilian Tayenthal. It launched as one of Europe’s first mobile-first banks and now serves millions of customers in 24 European markets. It holds a full German banking license, regulated by BaFin — Germany’s Federal Financial Supervisory Authority — which is one of the more rigorous regulatory bodies in Europe.
That licensing detail matters more than it might seem. Your deposits with N26 are protected up to €100,000 under the German Deposit Guarantee Scheme. This puts N26 in a different regulatory category from some of its fintech competitors.
It’s worth noting that N26 left the UK in 2020 and the US in 2022, choosing to concentrate on its European core. It operates in 24 European markets, so if you’re in Europe, you’re likely covered.
Plans and Pricing
N26 offers four tiers. The free plan is genuinely functional — not a stripped-down teaser designed to push you to paid.
Standard — Free
No monthly fee. You get an N26 Mastercard, a German IBAN (plus local IBANs in certain markets like Spain), Apple Pay and Google Pay, real-time transaction notifications, and basic Spaces for saving goals. The card is virtual by default (a physical card costs €10 in Spain), and free ATM withdrawals in euros are limited to 2 a month in Spain. For light use or as a secondary account, this is perfectly workable.
Smart — €4.90/month
Adds up to 10 Spaces sub-accounts, Shared Spaces for splitting expenses with others, and customer support via in-app chat. A sensible middle tier if you want more savings organization without jumping to the full travel bundle.
Go — €9.90/month
Adds travel and purchase protection insurance, more ATM withdrawals, and partner perks. Aimed at frequent travelers who want basic coverage baked into their banking.
Metal — €16.90/month
The premium tier. You get a metal Mastercard, more comprehensive travel insurance (including medical, flight delay, and car rental), higher ATM limits, and priority customer support. Comparable to Revolut Premium or Ultra in positioning, though the feature set is more focused.
Key Features
Desktop and Web Access
This is N26’s single biggest practical advantage over Revolut, and I want to give it the emphasis it deserves.
You can log into N26 from any browser, on any computer, and do everything: view your balance and transaction history, manage Spaces, transfer money, check statements, update your settings. It works like a real bank’s online portal — because it is one.
If you work from a laptop and want to check your finances without picking up your phone, N26 handles this well. It sounds like a small thing until it isn’t — it’s handy when reconciling expenses or making transfers from a desk.
Spaces
Spaces are sub-accounts you can create within N26 to ring-fence money for specific goals — a holiday fund, an emergency buffer, a tax reserve. The free plan gives you a couple; paid plans go up to 10. They’re simple and well-executed. You can set targets, move money between them, and see your progress at a glance.
Shared Spaces (available on Smart and above) let you create a shared sub-account with another N26 user — useful for splitting rent, joint trips, or shared expenses without a joint current account.
Savings Accounts
N26 offers savings accounts with competitive interest rates depending on your plan and country. These are held within N26 itself, not via a third party, which keeps things simple. The rates aren’t the highest available, but the convenience of having savings and spending in one place is worth something.
International Transfers via Wise
For international transfers, N26 integrates directly with Wise (formerly TransferWise). You can send money abroad from within the app, using Wise’s transparent fee structure and competitive exchange rates. This is a better international transfer experience than most traditional banks offer by a significant margin. The fees are shown clearly upfront, and the mid-market rate is used where possible.
Spending Analytics and Transaction Categorization
Every transaction is automatically categorized — food, transport, entertainment, and so on. Monthly spending breakdowns give you a reasonable picture of where your money goes. It’s not as granular or customizable as some dedicated budgeting apps, but for built-in analytics it’s more useful than most banks provide.
Card Controls
You can freeze and unfreeze your Mastercard instantly from the app. You can also toggle individual transaction types on or off — contactless payments, online purchases, ATM withdrawals — which is useful if you want to lock down your card while traveling or in a period of low use.
Local IBANs
In Spain and a number of other markets, N26 provides a local IBAN, not just a German one. This matters practically: some Spanish employers, landlords, and direct debit billers won’t accept foreign IBANs (a persistent frustration with fintech banks historically). A local IBAN removes that friction entirely, which makes N26 more viable as a genuine primary or secondary account in everyday Spanish life.
Apple Pay and Google Pay
Both are supported across all plans. Setup takes a few minutes and works reliably. Standard for any modern bank at this point, but worth confirming if contactless payments matter to you.
Security and Regulation
N26 takes a layered approach to security that covers the main bases:
- Biometric authentication — Face ID and fingerprint login
- PIN protection for sensitive actions
- Instant card freeze/unfreeze from the app
- Real-time push notifications for every transaction
- Granular card controls (toggle contactless, online, ATM independently)
- 3D Secure for online payments
The regulatory story is the strongest part. N26 holds a full German banking license and is regulated by BaFin — the same authority that oversees Deutsche Bank and Commerzbank. Your deposits up to €100,000 are protected under the German Deposit Guarantee Scheme.
Compare this to Revolut, which holds a Lithuanian banking license. Lithuania’s regulatory framework is legitimate, but Germany’s BaFin is widely regarded as one of the more stringent financial regulators in Europe. If regulatory confidence is a deciding factor for you, N26 has a meaningful edge.
What N26 Does Well
The desktop interface is genuinely useful
Web access is one of the strongest reasons to pick N26. Being able to manage your account from a browser without jumping through hoops is a real advantage. It sounds basic. It shouldn’t be a differentiator in 2026. But it still is.
Clean, focused banking
N26 doesn’t try to be a super-app. Crypto, stocks, and ready-made funds are there in some countries, but they sit in the background. It wants to be a good bank first. For a lot of people, that clarity of purpose makes it easier to use and easier to trust. There’s less noise.
BaFin regulation and deposit protection
Already covered above, but it bears repeating. If you’re keeping meaningful savings with a neobank, the regulatory framework matters. N26’s German banking license is a genuine differentiator, not a marketing claim.
Wise integration for international transfers
Having competitive international transfers built directly into the app, powered by Wise, is a practical win for anyone who sends money abroad regularly. The transparency of fees and rates is far ahead of traditional banks.
Local IBANs
For residents of Spain (and other supported markets), a local IBAN removes the compatibility headaches that have plagued other neobanks. You can use N26 for salary deposits and direct debits without needing a backup account at a traditional bank.
Where N26 Falls Short
The feature gap versus Revolut is real
N26 has added crypto (through Bitpanda), stocks and ETFs (through Upvest), a travel eSIM, and cards for under-18s. But crypto and investing are only offered in some countries, the range is narrower, and there’s no multi-currency account. Revolut has built a financial super-app over the past few years, and N26 hasn’t tried to match its breadth. That’s a deliberate choice, but it means N26 isn’t the right primary account for users who want those capabilities.
Exchange rates aren’t interbank
N26 uses Mastercard’s exchange rates for currency conversion — good, transparent rates, but not the mid-market interbank rate that Revolut offers. For heavy multi-currency spending or international travel, this is a real cost difference worth factoring in.
European-only
N26 withdrew from the UK in 2020 and the US in 2022. If you’re outside Europe, it’s not an option. Within its supported markets the service is solid, but the retreat from major English-speaking markets is a signal about the company’s scale ambitions.
Customer support has limits
Support is not 24/7, and on the free plan your access to live chat is limited. This is an area where N26 has improved over time but still lags behind what you’d expect from a bank handling serious account issues at any hour. For routine use it’s rarely a problem, but if something goes wrong on a Sunday evening, you may be waiting.
Smaller scale
N26 is a fraction of Revolut’s 70 million-plus user base. Scale affects product velocity, partner integrations, and long-term stability. N26 is a well-regulated bank, but the size gap is worth acknowledging honestly.
Family features are newer
N26 now offers debit cards for kids and teens, managed from the parent’s N26 app. Revolut’s under-18 accounts have been around for years and are more established, which matters if family banking is a priority.
Who Should Choose N26
N26 is the right choice — or a worthy addition to your setup — if any of these describe you:
- You want a European neobank with serious regulatory backing (BaFin, full German banking license, €100k deposit protection)
- You need desktop/browser access to your account as part of your regular workflow
- You live in Spain or another N26 market and want a local IBAN for salary and direct debits
- You want clean, focused banking without the complexity of a super-app
- You send money internationally and want Wise integration built in
- You want a simple secondary account to keep separate from your main spending
N26 is probably not the right primary account if you want a single app for investing, crypto, travel tools, and family accounts. For that use case, Revolut is the stronger choice.
Conclusion
I’ve used N26 for several years. It earns its place not by competing with Revolut on features, but by doing something different and doing it well.
The desktop access is the practical hook. Being able to log in from a browser and manage the account properly — without the mobile-only friction that still plagues some fintechs — is a genuine quality-of-life improvement. Paired with the strongest regulatory story in the neobank space and a clean interface that doesn’t overwhelm, N26 is a bank I trust.
It won’t replace Revolut for day-to-day spending and travel. But as a secondary account with real banking infrastructure behind it, it’s a smart addition — particularly if you’re based in Europe and care about where your deposits actually sit.
The free plan is worth trying with no commitment. If you find yourself using it regularly, the Smart tier at €4.90/month is a reasonable upgrade. The Metal card is best reserved for frequent travelers who’ll actually use the insurance benefits.
If you’re comparing N26 and Revolut side by side, I’ve put together a detailed breakdown: N26 vs Revolut.
Frequently Asked Questions
Is N26 safe?
Yes. N26 holds a full German banking license and is regulated by BaFin, one of the most rigorous financial regulators in Europe. Your deposits are protected up to EUR 100,000 under the German Deposit Guarantee Scheme. This puts N26 in a stronger regulatory category than some fintech competitors. Security features include biometric authentication, instant card freeze, real-time transaction notifications, and 3D Secure for online payments.
Is N26 free?
The Standard plan is completely free and genuinely functional. You get an N26 Mastercard, Apple Pay and Google Pay support, a German IBAN (plus local IBANs in some markets like Spain), real-time notifications, and basic Spaces for saving goals. Paid plans start at EUR 4.90/month (Smart), EUR 9.90/month (Go), and EUR 16.90/month (Metal), adding features like more Spaces, travel insurance, and priority support.
Does N26 have a desktop or web interface?
Yes, and this is one of N26’s biggest practical advantages over competitors like Revolut. You can log into N26 from any browser and do everything: view balances, manage Spaces, transfer money, check statements, and update settings. It works like a proper online banking portal. This is particularly useful for managing finances from a laptop when reconciling expenses or making transfers.
What countries is N26 available in?
N26 operates in 24 European markets, including Austria, Belgium, France, Germany, Ireland, Italy, the Netherlands, Portugal, and Spain. It left the UK in 2020 and the US in 2022 to focus on its European core. In Spain and some other markets, N26 provides a local IBAN in addition to the German IBAN.
How does N26 handle international transfers?
N26 integrates directly with Wise (formerly TransferWise) for international transfers. You can send money abroad from within the N26 app using Wise’s transparent fee structure and competitive mid-market exchange rates. Fees are shown upfront before you confirm. This is significantly better than what most traditional banks offer for cross-border transfers.
How does N26 compare to Revolut?
N26 offers a full desktop interface that Revolut still lacks, stronger regulatory backing (BaFin German banking license vs. Lithuanian license), and a cleaner, more focused banking experience. Revolut offers a broader feature set, including multi-currency accounts, a wider investing and crypto range, travel booking, and a robo-advisor. N26 has added crypto, stocks, a travel eSIM, and under-18 cards, but not all of them in every country. N26 uses Mastercard exchange rates for currency conversion rather than Revolut’s interbank rate. N26 works best as a complement to Revolut, not a replacement.
Summary
My online bank of choice at the moment. It works really well and provides all the facilities I need from an online bank. As a bonus, N26 also provides local IBAN numbers to those living in Spain, which greatly facilitates direct debits.
Pros
- Fantastic app.
- Good support.
- Lots of extras.
Cons
- No physical branches of this bank - if that's a concern.
- Not crypto-friendly.
Related



Is it possible to obtain a mortgage for Spain in N26 if I make it the account which receives my monthly Norwegian pension?
Hi Jean,
Great article. Do you know if I opened an N26 account I’d have to submit a new Modelo 720 declaration?
Thanks
No you don’t, they will give you a Spanish IBAN.
Thanks Jean !
Paul
I tried opening an account.
Not available in Malta as yet.
They put me on the waiting list.